Working with your insurance after water, fire or mold damage
We will work with any insurance carrier you use. RMO works directly with carriers and adjusters, documenting the damage and the work so your claim can be reviewed on the facts and cover the whole job. Your insurer decides what is covered, and the claim stays yours.
24-hour emergency hotline248-845-0000A person answers, day or nightWe take pride in getting your claim right
We will work with any insurance carrier you use. Over the years we've worked through claim after claim with homeowners, property managers and building owners, and it is a part of the job we take pride in.
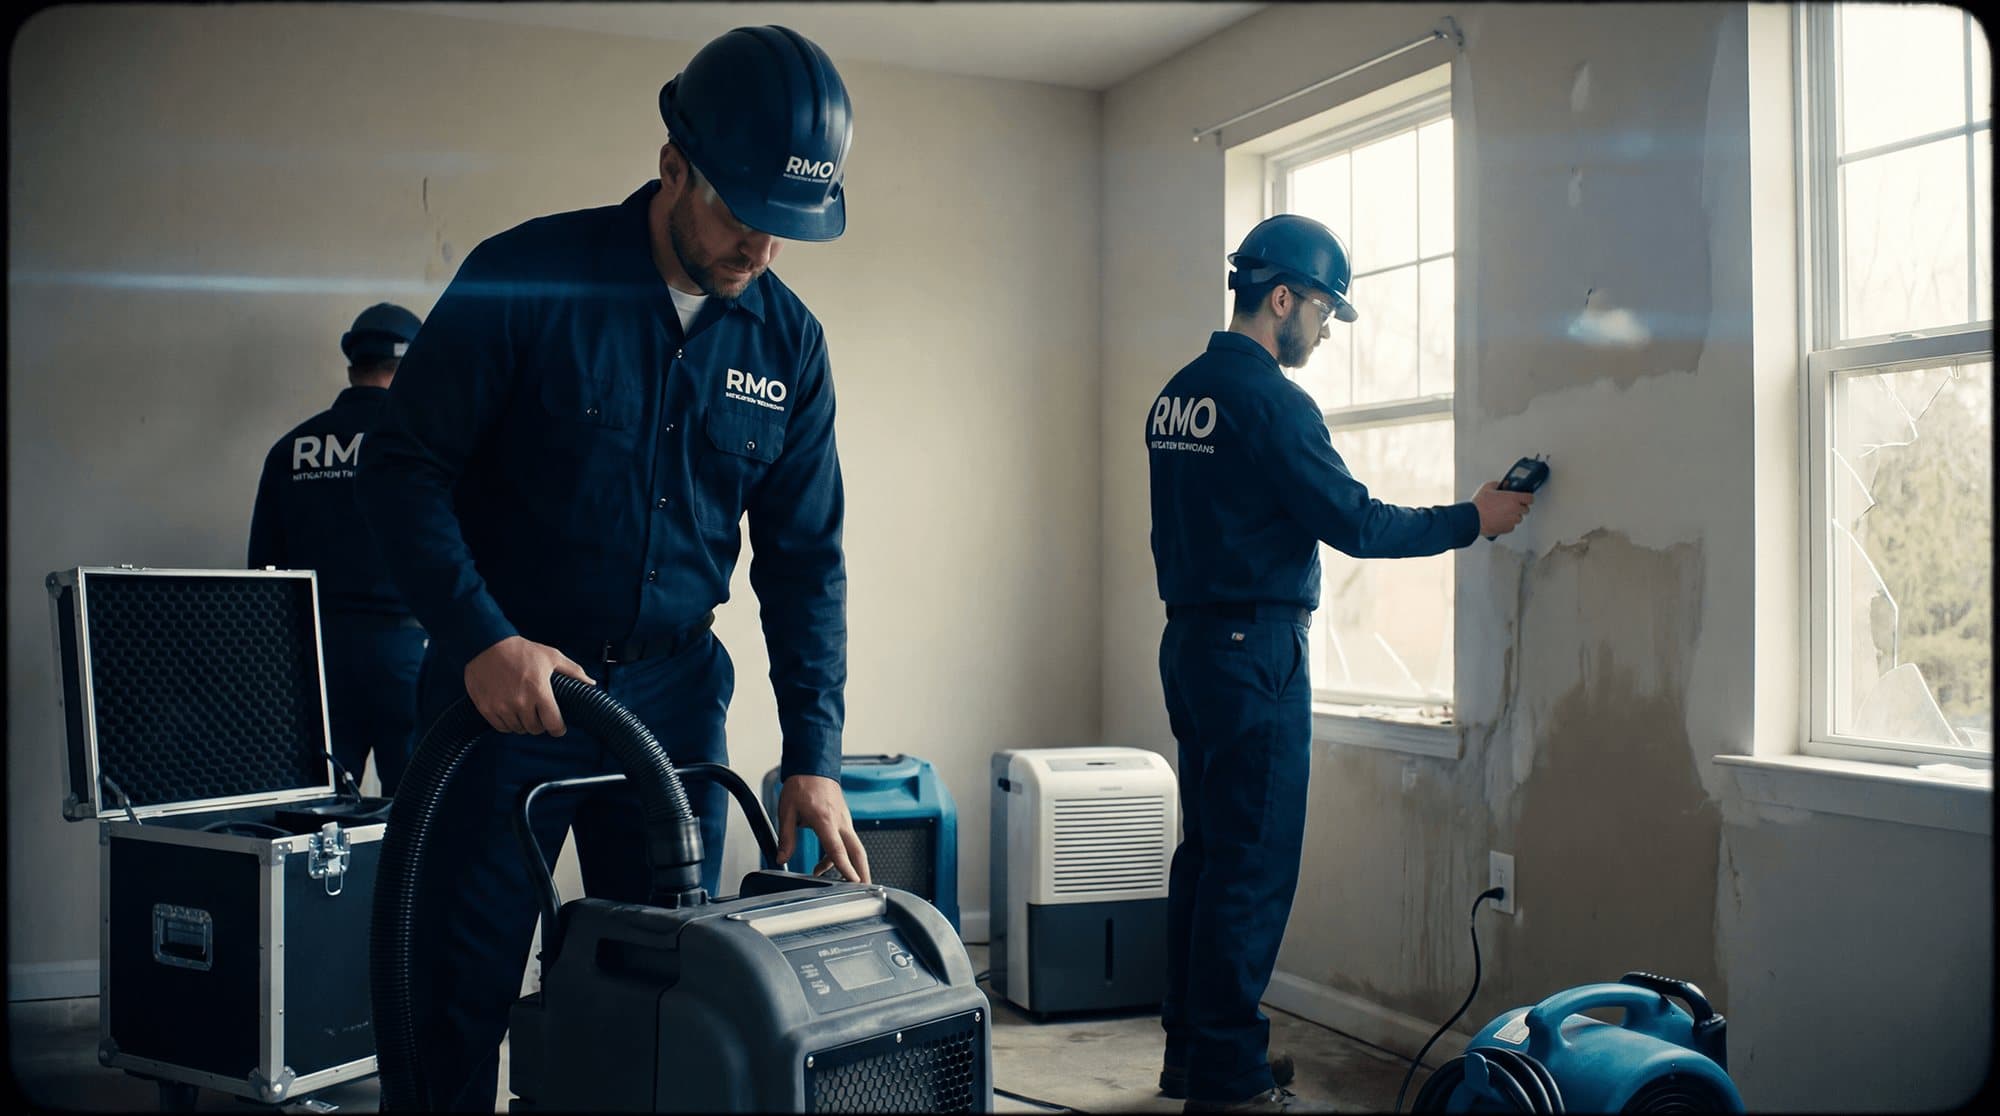
Every job is documented from the first hour: photos, moisture readings, drying logs and an itemized scope your adjuster can check line by line. We meet adjusters on site, answer their questions and keep the file complete, so nothing the policy covers is left off the claim. We try our hardest to make sure insurance covers the entire project.
That work pays off for our clients. Many have saved thousands of dollars, and on many jobs the claim covered the whole project and the client paid nothing beyond their deductible.
We will work with your insurance
We will work with any insurance carrier you use. We’ve done it on claim after claim, and we take pride in it: every job is documented from the first hour and priced line by line, and we work hard so your insurance covers the whole project.
Many of our clients have saved thousands of dollars this way, and many paid nothing beyond their deductible.
How we help with insurance claims
Examples of carriers our customers use. RMO is an independent company and isn’t affiliated with or endorsed by these insurers.
The first hours after damage
- 01
Make it safe
Leave if the building is unsafe. Don't enter a burned building until the fire department clears it. Turn off power only if you can reach the panel without standing in water, and keep people and pets away from sewage.
- 02
Stop the source if you can
Close the main water shut-off for a burst pipe or a failed water heater. If you can't find it or reach it safely, tell us when you call.
- 03
Photograph before anything moves
A few minutes of photos now can answer an adjuster's questions later. The checklist below covers what to capture.
- 04
Call us, then your insurer
Call 248-845-0000 so we can stop the damage, then report the loss to your insurance company as soon as you can. Write down your claim number and your adjuster's name.
- 05
Keep receipts
Save receipts for emergency costs such as a hotel stay, meals or supplies, and ask your insurer what your policy covers.
What to photograph
Take wide shots first, then close-ups. Photograph damage before it is moved or thrown out.
- Each affected room from the doorway, then from the opposite corner
- Water lines on walls, cabinets and furniture
- The source: a burst pipe, failed appliance, roof opening or backed-up drain
- Standing water, with a tape measure in the shot to show depth
- Damaged belongings, including brand and model labels where you can see them
- Ceiling stains, drips and sagging areas, taken from a safe distance
- Outside damage to the roof, siding, gutters or trees
How RMO documents your loss
From the first visit, we keep the record an adjuster expects to see.
Photos
The damage as we found it, materials as they are removed and the finished work.
Moisture readings
Readings at marked points and thermal images that show where water has spread, including behind walls and under floors.
Drying logs
Daily temperature, humidity and moisture readings, and the equipment in place, until materials reach their drying goals.
Itemized scope
Line by line, what was done and why, so the adjuster can compare it with their own estimate.
Working with your adjuster
We can meet your adjuster on site, share the job file and answer questions about the work.
What stays your decision
You decide whether to file a claim, which contractor works in your property, whether to accept a settlement, and which materials and finishes go back in during the rebuild. Questions about what your policy covers belong with your insurer or agent. We don't interpret policies or predict what a claim will pay.
If you have a question about your policy, or a dispute you can't resolve with your insurer, Michigan's Department of Insurance and Financial Services (DIFS) helps consumers with insurance questions and complaints.
Insurance questions
Can work start before the adjuster visits?
Usually, yes. Stopping the water, extraction and setting up drying shouldn't wait, and policies generally ask you to protect the property from further damage. We photograph and measure everything first. Repairs and rebuild usually wait until the scope is agreed with your insurer.
Will my insurance cover the damage?
That depends on your policy and on what caused the damage. A sudden burst pipe is often treated differently from flooding or a sewer backup, which may need separate coverage. Your insurer or agent can tell you what your policy says.
Can you promise my claim will be approved?
No. Only your insurance company decides what is covered and what it pays. What we can do is give your adjuster complete, accurate documentation of the damage and the work.
We will restore your property
Request a call and we’ll contact you soon
Leave your name and number and a coordinator will call you back. If water is still coming in, or there’s smoke or sewage, call now.
Call 24/7248-845-0000- A person answers 24/7
- On site in about 60 minutes
- We work with your insurer
Your details
Only your name and phone number are required.